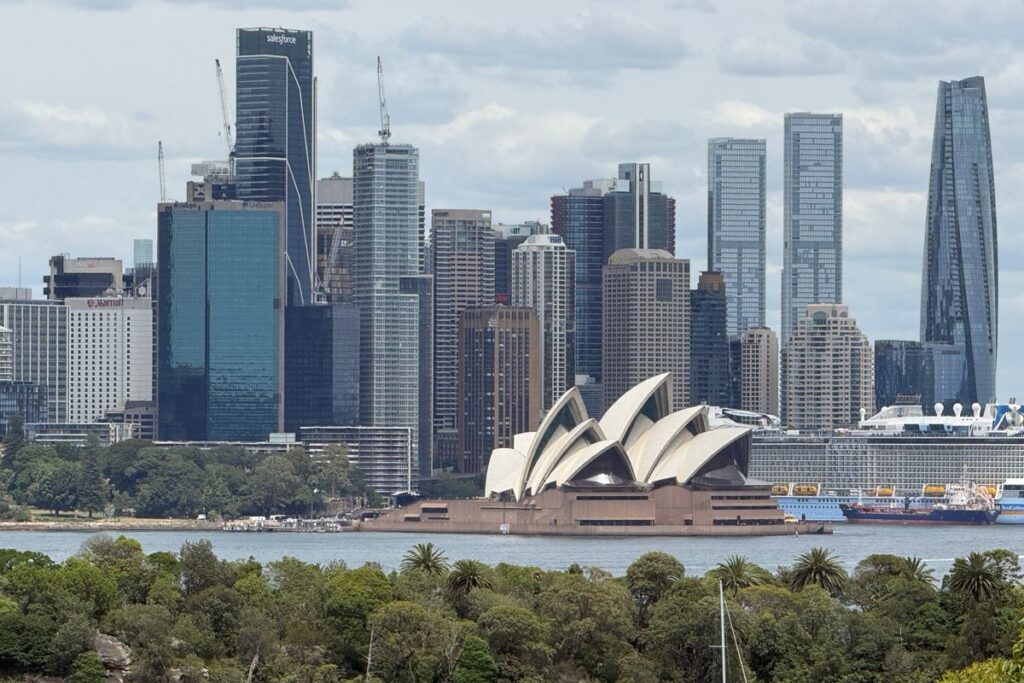
Australia’s hotel development pipeline tells an unusual story for 2026: demand is recovering strongly, but new supply is not keeping pace, and the gap between the two is wide enough to matter to anyone supplying the sector. For an Indian mill weighing whether Australia is worth the freight and lead-time cost of entry, that supply-demand imbalance is the single most important data point.
A constrained pipeline, not a stalled one
CBRE’s 2026 hotel sector outlook puts 5,143 rooms currently under construction nationally, with roughly 2,034 rooms delivered across 2025 and the portion of 2026 to date. That’s meaningful activity, but the pipeline thins sharply beyond 2027 — only three projects totalling 828 rooms are under construction for delivery after that point. Elevated construction costs, labour shortages and difficult financing conditions are the structural reasons cited for the slowdown, and none of those pressures look like they’re easing quickly.
Why the gap matters more than the raw numbers
CBRE’s own forecast is blunt about the mismatch: future room supply is projected to run 41% below historic delivery levels and 35% below forecast demand growth. That combination — strong demand, thin supply — is exactly the environment that pushes existing hotels toward renovation and refurbishment cycles instead of waiting on new builds, since operators competing for guests in a tight-supply market have every incentive to keep their existing rooms competitive rather than lose share to better-presented competitors.
What’s actually driving demand
International visitation has climbed back to around 92% of pre-pandemic levels, domestic travel has stayed resilient, and corporate and MICE (meetings, incentives, conferences and exhibitions) demand is accelerating on top of that. RevPAR growth is running above 8% across major cities, with Sydney and Brisbane leading, and a run of major sporting, cultural and business events is adding further occupancy and rate premiums through the outlook period. None of this shows up as a new hotel opening — it shows up as existing properties working harder to justify higher rates, which is a refurbishment and quality-upgrade story more than a new-build one.
Where this points for a bed and bath linen supplier
A constrained new-build pipeline means the addressable opportunity for an Indian mill isn’t primarily “supply the new 300-room tower” — there simply aren’t many of those in the pipeline right now. It’s the much larger, steadier base of existing hotels refreshing linen programmes to support higher rates and compete in a supply-constrained market, plus the handful of larger new developments that are moving forward despite the headwinds. That’s a less headline-grabbing opportunity than a giga-project pipeline, but it’s arguably a more resilient one, because refurbishment cycles happen on a recurring basis regardless of the broader construction environment.
The honest read for a mill evaluating this market
Australia isn’t a market where an Indian mill wins by chasing a handful of large new-build tenders — there aren’t enough of them to build a strategy around. It’s a market where the win comes from positioning for the ongoing refurbishment and quality-upgrade cycle that a tight-supply, strong-demand environment naturally generates, backed by the freight-and-lead-time discipline that ANZ sourcing requires regardless of which segment you’re chasing.