Supplier Notes · Market Notes · Kenya & East Africa
Kenya’s textile market runs on a contradiction worth understanding before dismissing it as a difficult place to export into: the country produces less than 12 million square metres of woven fabric a year against domestic demand of roughly 171 million square metres, making it a large net importer of textiles almost by structural necessity — and yet the East African Community’s tariff regime is actively designed to make importing finished textile goods more expensive, not less. For an Indian mill willing to understand that regime rather than avoid it, the gap between local production and local demand is exactly the opportunity.
The tariff reality: protection for local manufacturing, not a barrier aimed at India specifically
The EAC Common External Tariff (CET) runs a four-band structure — 0%, 10%, 25%, and a top band of 35% introduced to protect and encourage regional manufacturing. Finished textile goods have historically sat in the higher bands, and industry bodies within the EAC have specifically proposed moving textiles into the top 35% band, citing Kenya’s own limited fabric production capacity as the reason to reduce import dependence over time. Effective 1 July 2026, the EAC’s latest gazette also extended duty remission — 0% and 10% rates — on raw materials and inputs specifically for garment and made-up textile manufacturing, a measure aimed at encouraging local finishing rather than local production from scratch.
The practical read for an Indian supplier: this tariff structure is not a bilateral barrier aimed at Indian goods — it applies to finished textile imports from any origin equally, since India has no preferential trade agreement with Kenya or the EAC bloc lowering the finished-goods rate below what any other exporting country pays. That’s a genuinely different situation from the origin-specific advantage CEPA gives Indian goods into the UAE, and it should be priced into quotes honestly rather than assumed away.
A tariff that applies equally to every exporting country isn’t a reason to avoid the market — it’s a reason to compete on the same terms China does, and China’s cost base has moved in India’s favour over the past several years.
Why India’s cost edge over China still matters here
Because the EAC’s finished-goods duty band applies uniformly regardless of origin, the deciding factor for a Kenyan or East African hospitality buyer comparing suppliers isn’t which country has better duty treatment — nobody does — it’s landed unit cost. India’s raw cotton availability and labour cost structure have kept its textile export pricing more stable than China’s over the past several years, as Chinese wage growth and environmental compliance costs have pushed mid-range textile manufacturing costs upward. For hospitality-grade bed linen and terry towelling specifically, that shift has made India increasingly price-competitive into markets, like East Africa, where duty treatment doesn’t favour any single origin.
A hospitality sector that’s genuinely growing
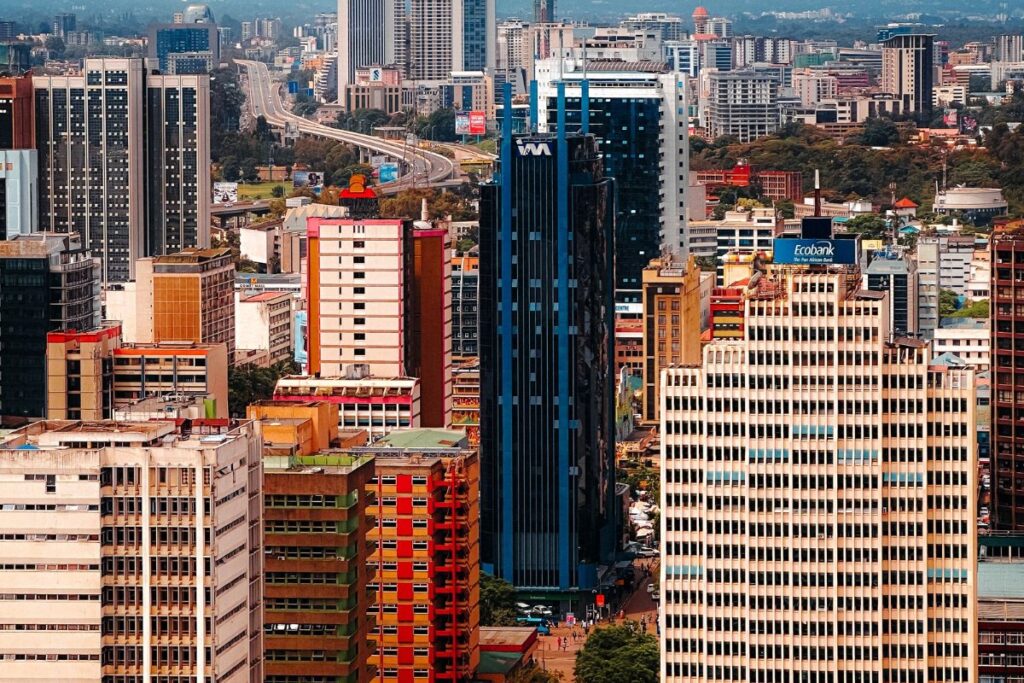
Kenya’s tourism and hospitality sector has continued expanding, with Nairobi’s conference and business-travel hospitality segment and the coastal leisure market both drawing continued hotel investment. Combined with the broader East African Community’s roughly 300 million-person market — Kenya, Uganda, Tanzania, Rwanda, and Burundi, all operating under the same CET framework — a supplier relationship built correctly in Kenya has a plausible path to regional reach across EAC partner states, not just a single-country account.
What a mill entering this market should get right from the start
- Quote landed cost with the applicable EAC finished-goods duty band included — don’t assume raw-material remission rates apply to a finished hospitality-linen shipment; they generally don’t.
- Watch the regulatory calendar. EAC CET rates and sensitive-goods classifications are reviewed and gazetted annually, effective each 1 July — a rate quoted from last year’s schedule may not be current.
- Position on total cost and consistency, not on a duty advantage that doesn’t exist — the argument for India here is landed price and GSM reliability against China and Turkey, made honestly rather than through an assumed tariff edge.
Celeris Exim tracks current EAC tariff classifications and works with Kenyan and East African hospitality buyers to build accurate landed-cost comparisons before quoting — so a supplier relationship starts on numbers that hold up, not ones that need correcting later.
Sources: “Kenya’s Textile Sector to Be Hit by EAC Sectoral Council Tax Proposal,” Fibre2Fashion · KPMG, “East African Community: Customs and Duty Changes for the 2026/2027 Tax Year” · PwC Kenya, “Tax Alert: Customs Changes, EA Community Gazette,” July 2026